You've done the hard part of going public. Finish it.
A Reg A+ offering means a qualified offering statement, audited financials and, for most issuers, ongoing reporting. You've pulled the first of the four levers, capital. The other three, talent, opportunities and acquisitions, are what make the raise the right decision, and they are far stronger once your shares trade.
Led by Joel Arberman, who has taken 17 companies public, several of them his own, eleven of them by direct listing.
Apply for the Program How it works
Planning a Reg A+ offering but haven't filed yet? Start with The Four Levers Program; the plan comes before the offering. Raising under Reg CF instead? That page is here.
You sold shares to the public. That is not the same as being a public company.
Your offering statement was qualified. Your financials are audited. If you're a Tier 2 issuer, you're already filing reports. You raised, or are raising, real money from a wide shareholder base, and you've paid the professional fees that come with all of it.
What you don't have, unless you've taken one more step, is a market for the shares you sold. Your investors hold a position they can't price or sell. Your stock can't recruit anyone, because nobody can value it. And every acquisition you might make has to be paid for in cash you would rather keep.
The distance from where you are to a listed company is shorter than it is for almost any private company. The questions are which market, at what price, and what you will do with the structure once you have it.
What changes when a company your size is public.
Capital is one of the four levers that grow a company. You've pulled it, and that's a real achievement. The other three are what make the raise the right decision, and a smaller company gets far more out of all three as a public company than it can as a private one.
Talent
Stock with a market price is something a senior hire, an industry veteran or a sought-after adviser can weigh. Private equity in a young company is a promise; listed stock is a number. One founder had spent months trying to hire a president who wanted a share of the company. A week after he committed to going public, the same candidate accepted options at a fixed price, on the same salary and bonus.
Opportunities
Partners, lenders and suppliers can check a public company without asking; the financials are already on file. When you can't reach the customers, recruit the people who already know them. One company brought on six or seven advisers with thirty years each, for options and no cash. They helped position the company better and connected it with prospective clients it would not otherwise have reached.
Acquisitions
Stock becomes one more way to pay, and a Reg A+ company often has the size to use it. Owners ready to sell will consider shares they can price, alongside cash, a note or a preferred share, from a transparent public company; they rarely would from a private one nobody knows. Outside investors can fund the cash portion, directly or through a special purpose vehicle. You can have your price or your terms, but not both, and a public company has more terms to offer.
Capital gets easier too: a listed company with a reporting record can raise its next round on better terms than the one before. That is the lever you already know. The other three are where the value gets created, and they are the reason to finish what the offering started.
Your investors will ask how they ever get their money out.
Sooner or later, every one of them asks, and the answer gets harder to give with every round.
A Reg A+ company can usually give its shareholders a market sooner than it expects. What a listing does not do is set the price; the business does that. We help you understand which of your shares can trade, and under what rules, before you say anything to investors, and what you say is a matter for your securities counsel.
Nasdaq is the listing you have probably heard about. For most Reg A+ companies it is the wrong first step.
A Nasdaq listing brings requirements the OTC market does not: board committees, paid independent directors, directors' insurance, and higher legal, audit and listing fees. In our experience the difference can be half a million to a million dollars a year or more.
The second problem is specific to companies that raised well. A Reg A+ raise at a strong valuation, followed by another at a stronger one, then a Nasdaq listing at the top, asks the public market to support a price set by your own investors. If the market disagrees, the stock falls, and with it every advantage above. Listing earlier, on the OTC market, at a price the business supports, gives you years to build value before you ask a larger exchange to ratify it.
Most of the companies our founder has taken public listed on the OTC market first, by direct listing, at modest valuations, and built from there. Some later moved up to Nasdaq when the business had earned it. One went from a $3.5 million listing to a $240 million sale.
If you're building it, it holds. If you're inflating and you list, it pops.
What a Reg A+ company usually has to add before it lists. It is less than you think.
A listing plan, not just a filing
You have the disclosure. What is usually missing is the decision: which market, at what price, with which shareholders, and what you will do with the structure in the first 36 months.
The remaining steps to quotation
Depending on your tier and what you have already filed, the steps to quotation on the OTC market can be short. We map them with your counsel; the specifics are theirs to confirm.
Shareholder and cap-table hygiene
A wide Reg A+ base is an asset for a listing. It still has to reconcile cleanly with the transfer agent, and the rules for which shares can trade have to be understood before anyone is told anything.
Investor communication fit for a public company
Plain reporting of results, the good and the bad, with a clear deck, website and investor section. Not promotion.
Most Reg A+ companies can list. Not all of them should list now.
A good fit if you
- Are raising, or have just raised, under Reg A+, and have done what your offering statement said you would do so far
- Have audited financials and, if Tier 2, are current in your reporting
- Have a use for talent, partners or acquisitions in the next two to three years, and the management to act on it
- Are prepared to run the company with the transparency and governance a listing brings
Probably not yet if you
- Are mid-offering and the offering itself is not going to plan
- Have a milestone you should hit first, gaps in the team, or an approval you're still waiting on
- Are being advised to list on Nasdaq at your current valuation and haven't yet looked at the cost
- Expect a listing to deliver a price. It gives your shares a market. The business sets the price.
Not ready yet? The Four Levers Program still applies. It tells you how to pull the levers while private, what would need to change before a listing makes sense, and in what order. A clear "not yet" is a good outcome for $10,000 too.
How it works
Four steps, in order. Every step is optional and agreed in writing before it starts. You can stop after any step and owe nothing further.
Plan: The Four Levers Program
Four one-to-one working sessions and a written playbook built around your company: a straight verdict on listing now, later or never; the OTC market or Nasdaq, and why; the remaining steps from your current filings to a quoted stock, mapped with your counsel; your 36-month plan for the other three levers; and a 90-day action list. About 30 days. $10,000, fixed, and nothing owed after. Read about the program.
Raise
You're already raising, so this step is usually skipped. If the plan calls for another round before a listing, Raise-Ready is $15,000, fixed, with 90 days of support.
List
For most Reg A+ companies this is a direct listing on the OTC market, and the sequence is shorter than for a company starting from private. We manage it and coordinate the auditors, securities lawyers, transfer agent, market maker and other specialists. A monthly fee plus equity, agreed in writing before it starts.
Build
Once you're public, ongoing strategic advice on the three levers: hiring with stock, partnerships, acquisitions, investor communication, and moving up to a larger exchange when the business has earned it. A monthly fee plus options.
What it costs. Every engagement starts with The Four Levers Program: four one-to-one working sessions and a written playbook, about 30 days, $10,000 fixed, with nothing owed after. If the plan calls for a raise, Raise-Ready is $15,000, fixed, with 90 days of support. Listing, and the advisory work after it, are on a monthly fee plus equity, agreed in writing before each step starts. You can stop after any step and owe nothing further.
Third-party costs are additional and paid directly to those providers: accounting, audit, legal, stock exchange, transfer agent and filing fees. We'll estimate them once we've seen your financials. As a guide, a direct listing typically runs $300,000 to $500,000. For a company that already has an audit and current filings, it is often at the low end of that range.
You don't need this money sitting in the bank. In almost every case, the private placement is structured so you and your team can raise capital from your personal and professional networks to cover these costs. Your own outlay is the plan and the preparation.
What this is not.
We don't raise money or sell stock
We're not a broker-dealer, we have no investor list, and we never contact your investors.
We don't promote stocks
We help you report results plainly, the good and the bad.
We don't write your offering materials
Anything you tell investors about a future listing is a disclosure matter for your securities counsel and your offering documents. The playbook informs your plan; your counsel decides what goes in front of investors.
Who you'd be working with
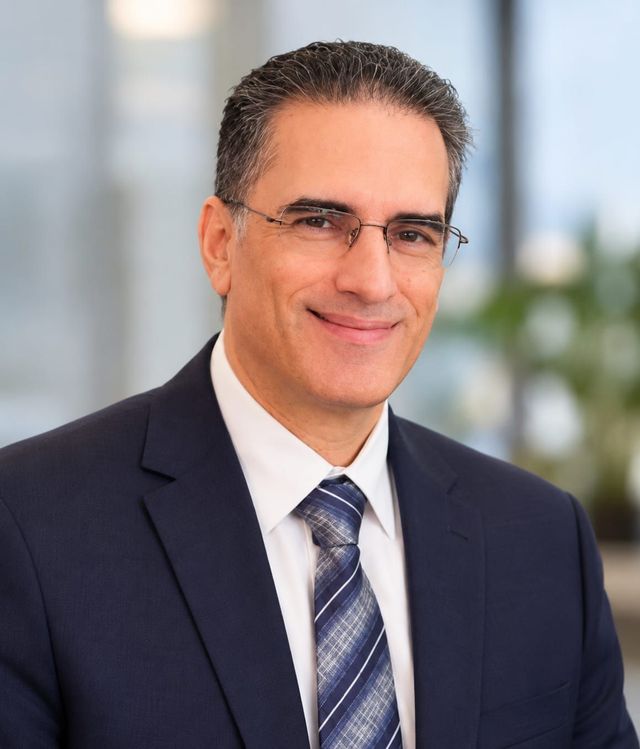
I'm Joel Arberman. In 1999 I took my own startup public with almost no money, writing the registration statement myself because nobody would help a company that small. Once our shares traded, a development firm took half its fee in stock, a PR agency took all of its fee in stock, a well-known venture capitalist joined our board for options, and we bought another company entirely with stock.
Before that I was an equity analyst in New York and, at 22, a partner at a 700-person investment bank. Over more than 30 years, across Wall Street, Bay Street and my own companies, I've taken 17 companies public, several of them my own and a dozen with no revenue. I'll tell you honestly whether this fits your company, and if it does, I'll be beside you for every step.
Questions founders ask.
Our offering was qualified. Aren't we already public?
You sold shares to the public, and you may already report. A public company whose shares trade is a separate step, and for you it is usually a short one.
We've been told Nasdaq. Why do you say OTC?
Because of what it costs to stay there, and because a Nasdaq listing at an investor-set valuation asks the market to support a price it has not tested. We'll walk through the numbers for your company; the decision is yours.
We're mid-offering. Should we wait until it closes?
The plan is more useful before it closes, because the listing decision affects the terms of the round and what you can say about what comes next. The listing itself usually waits for the close.
Which of our shares will trade?
It depends on your tier, what you filed, and the rules that apply to each holder. We map it with your counsel before anyone is told anything, and we don't promise liquidity.
What if the verdict is "not yet"?
Then you'll hear that, with the reasons, and the playbook covers how to pull the four levers without a listing, or what would need to change first.
You've done the hard part. Finish it, and use it.
Apply for The Four Levers Program. If we're not the right fit, we'll say so on the first call.
Request a first call.
Tell us about you and what you're building, and we'll set up a first conversation if it looks like a fit. No cost, no obligation.